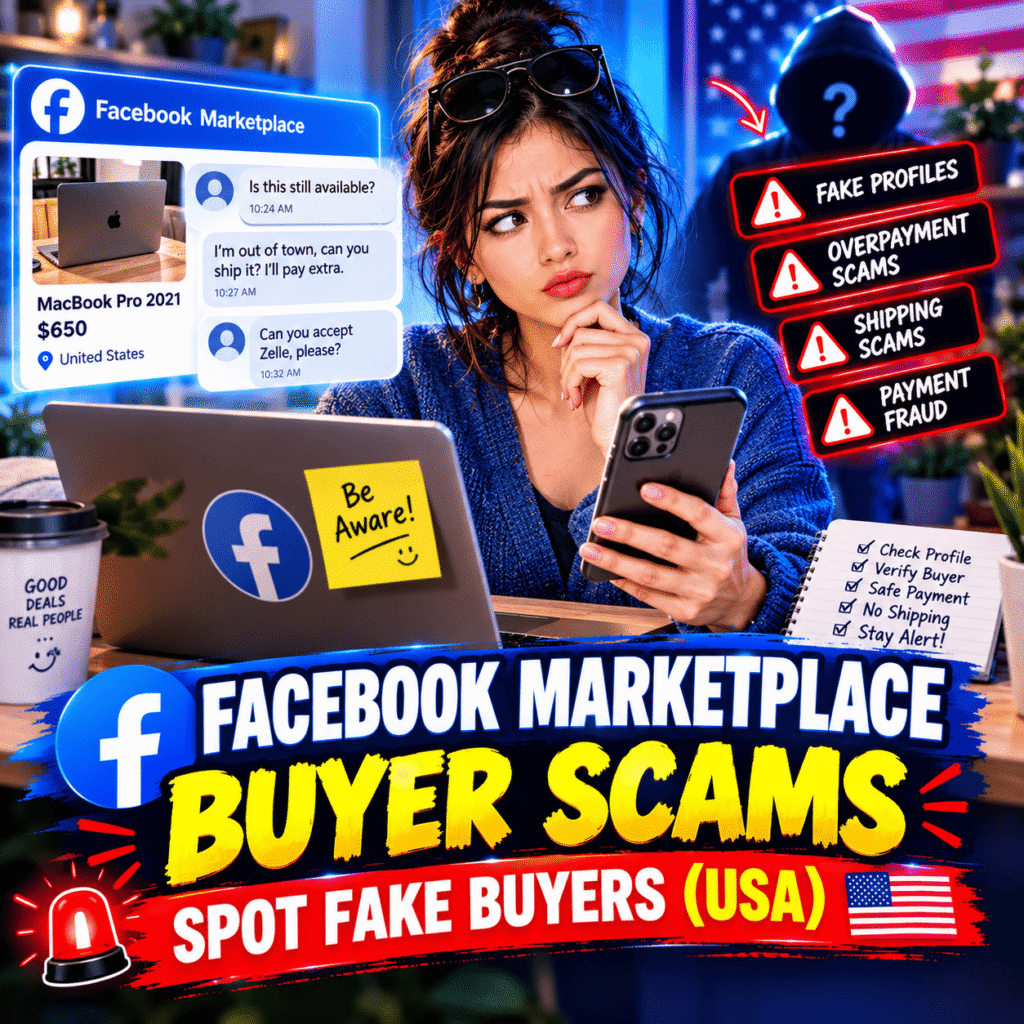
Common Facebook Marketplace Scams in the USA: Full Guide
📅 Published: October 2026 | ⏱ Reading Time: ~25 Minutes | 🗂 Category: DIGITAL WORLD | 👥 For: Buyers and sellers in the USA
Imagine you’re selling a $300 sectional sofa from your apartment in Mesa, Arizona. Four minutes after you post it, a buyer writes back: “I’ll take it, no haggling.” A Zelle screenshot arrives next, then a rushed note about a mover coming tonight. Everything feels smooth until you open your bank app and the money isn’t there.
That story, or one very close to it, plays out somewhere in America every day. In 2025, consumers reported losing $15.9 billion to fraud, up from more than $12 billion the year before, according to the FTC’s March 2026 testimony summary. The agency also says reported losses are only a fraction of the real total, because most people never file a report.
Social media is where a big share of it begins. The FTC’s April 2026 Data Spotlight on social media scams found that nearly 30% of people who reported losing money said the scam started on social media, with reported losses reaching $2.1 billion in 2025. Facebook produced more reported losses than any other platform, roughly $794 million, and shopping scams were the most reported type. On top of that, the FBI’s Internet Crime Complaint Center logged 56,478 non-payment and non-delivery complaints for 2025, with about $503 million in reported losses.
This guide is written for buyers and sellers across the United States. You’ll get the 10 most common scams on the platform, with dollar amounts, real red flags and a safer move for each one. You’ll also see which US agencies take reports, how federal rules like Regulation E and the Fair Credit Billing Act affect your odds of getting money back, and where to meet strangers in cities like Columbus, Atlanta and Austin. If you want a plain map of Facebook Marketplace scams in the USA, this guide is built to be that map.
Let’s get into it.
📋 Table of Contents
- Why Marketplace Is a Scammer Favorite in the USA
- Scam 1: Fake Payment Notices and Screenshots
- Scam 2: Overpayment and Fake Check Tricks
- Scam 3: The Google Voice Code Request
- Scam 4: Phishing Links and Fake Payment Pages
- Scam 5: Fake Listings, Deposits and Non-Delivery
- Scam 6: The Pay-First Payment App Trap
- Scam 7: Shipping, Fake Tracking and Fee Scams
- Scam 8: Car, Truck and Motorcycle Scams
- Scam 9: Rental and Housing Scams
- Scam 10: Bait-and-Switch, Counterfeit and Stolen Goods
- What Do These Scams Cost, and What Does Protection Cost?
- US Rules That Decide Whether You Get Your Money Back
- Scam Comparison at a Glance
- Safe Meetups: Where to Trade in Columbus, Atlanta, Austin and Beyond
- Where to Report a Scam in the USA
- How to Protect Yourself: Step by Step
- Real Stories: Buyers and Sellers Across the USA
- Red Flags and Mistakes to Avoid
- Free and Paid Tools That Help
- Quick Reference Checklist
- Frequently Asked Questions (FAQ)
- Final Thought
Why Facebook Marketplace Scams Keep Catching Americans
Marketplace works because it’s local, fast and free to list. Those same traits help scammers. Accounts are cheap to create, a buyer can reach you within seconds, and most deals happen in cash or by payment app with no paperwork at all. A stranger in Houston and a stranger in Boise look equally believable inside a chat window.
There’s also a trust problem. Because Marketplace lives inside Facebook, plenty of people assume the platform vouches for whoever is on the other end. It doesn’t. Meta says it removed more than 159 million scam ads and took down 10.9 million accounts tied to scam operations in 2025, and scammers still get through every day. The Better Business Bureau’s 2025 Scam Tracker data tells a similar story: online purchase scams made up nearly 30% of more than 146,000 published reports.
The good news is that scams on Facebook follow patterns. Learn five or six of them and most attempts fall apart within the first two messages.
- ✅ Fewer lost deposits. You’ll see why a $100 “hold fee” on a $400 item is a trap.
- ✅ Faster decisions. A short list of red flags lets you walk away in minutes.
- ✅ Smarter payment choices. Cash, checkout and credit cards each protect you differently.
- ✅ Safer meetups. Police-monitored exchange spots exist in cities like Columbus, Ohio and around Austin, Texas.
- ✅ A clear reporting path. You’ll know which US agency to contact first.
- ✅ Calmer selling. Knowing the playbook takes the guesswork out of every “Is this still available?” message.
Which Way of Paying Protects You Most?
| Feature | Local cash deal | Payment app deal (Zelle, Venmo, Cash App) | Shipped order with Meta checkout |
|---|---|---|---|
| Protection from Meta | ❌ Not covered (local pickups don’t qualify) | ❌ Not covered | ✅ Covered for eligible items up to $2,000 per purchase |
| Bank or card recourse | ❌ None with cash | ⚠️ Limited, often none for payments you authorized | ✅ Card or PayPal dispute rights may also apply |
| Main scam risk | Counterfeit bills, bait-and-switch, robbery | Fake payments, sellers who vanish | Phishing links that copy the checkout page |
| Best for | Furniture and small items, often under $500 (estimate) | Use only with people you know | Items under $2,000 that can ship |
| Beginner-friendly? | ⭐⭐⭐⭐ Yes, if you meet safely | ⭐ Risky with strangers | ⭐⭐⭐⭐ Yes, if you stay inside checkout |
Scam 1: Fake Payment Notices and Screenshots
This one targets sellers, and it moves fast. A buyer says they’ve paid. They send a screenshot, a forwarded email or a text that looks like it came from Zelle, Cash App or PayPal. The message claims the money is “pending,” or that you must upgrade your account before you can receive it. The FTC’s consumer alert for online sellers describes the same pattern: scammers send a fake payment notification and hope you hand over the item before you realize nothing arrived.
A screenshot is not a payment. Open your own banking or payment app, type the web address yourself, and look at your balance. If the money isn’t sitting in your account, the sale hasn’t happened. Don’t ship, don’t hand over the keys, and don’t click a link to “claim” funds.
How Can You Tell a Payment Is Real?
Only your own account can confirm it. Here’s what a fake payment typically costs a seller:
| Item sold | Example listing price | What the scammer walks away with |
|---|---|---|
| Used sectional sofa (Mesa, AZ) | $250 to $600 | The couch |
| Used iPhone (Tampa, FL) | $300 to $900 | The phone |
| Mountain bike (Denver, CO) | $400 to $1,500 | The bike |
| Power tool set (Columbus, OH) | $150 to $800 | The tools |
Price ranges are rough estimates for typical used listings, not figures from one source.
- The buyer agrees to your full price at once, with no questions about the item.
- You get a screenshot or forwarded email, but nothing shows in your own app.
- A message tells you to “upgrade” an account or tap a link to receive funds.
- Pickup or shipping is demanded within the hour.
Scam 2: Overpayment and Fake Check Tricks
A buyer offers more than your asking price. Maybe they send a check for $900 on a $600 desk, then ask you to wire back $300 “for the mover.” The check looks real, and your mobile deposit even shows the funds. But a deposit appearing in your balance doesn’t mean the check cleared. The FTC warns it can take weeks for a bank to spot a fake, and when it does, the bank pulls that money back out of your account.
Run the math. The $900 check bounces and disappears from your balance. The $300 you sent is already gone. Mobile deposits and payment app “overpayments” follow the same script, so the FTC’s rule applies to all of them: never deposit a check, or accept a mobile payment, for more than the selling price.
What Happens to Your Money?
| When | What you see | What is really happening |
|---|---|---|
| Day 1 | $900 shows up after a mobile deposit | The funds are provisional. Nobody has verified the check. |
| Day 1 | You send $300 by Zelle or wire | Your real money leaves for good |
| Days to weeks later | A notice about a returned item | The bank flags the check as fake |
| Result | $900 reversed, $300 gone | You may also face overdraft fees |
- Take cash in person, or a payment you can confirm inside your own app.
- Talk to your bank before accepting any check from a stranger.
- Refuse every “refund the difference” request, however polite it sounds.
- Save the chat. It shows intent if you report it later.
- Remember that a buyer who wants to overpay has already told you what they’re up to.
Scam 3: The Google Voice Code Request
A “buyer” says they’ve heard about fake listings and wants to confirm you’re a real person. They text you a six-digit Google Voice code and ask you to read it back. If you do, they use it to create a Google Voice number linked to your real phone number. Then they run other scams under that number, and if anyone traces it, the trail leads straight to you. The FTC lists this trick alongside fake payments and fake checks.
The Identity Theft Resource Center has heard from people selling puppies, hunting for lost pets and renting out rooms who got the same request. The story changes, but the ask never does: read me the code. No honest buyer needs it.
What If You Already Sent the Code?
| Warning sign | What it really means | Safe response |
|---|---|---|
| “I’ll text you a code to verify you’re real” | The code belongs to a Google Voice sign-up using your number | Don’t reply with it. Block the buyer. |
| “I don’t use Messenger, text me instead” | Moving to text makes code tricks easier | Keep the chat inside Messenger |
| “Just read me the six digits” | You’re handing over control of a number tied to you | Say no and report the profile |
- Use Google’s steps for reclaiming your number. The FTC points sellers to them.
- Watch for strange calls or texts tied to your number over the next few weeks.
- Change passwords on any account that uses that phone number.
- Report it to ReportFraud.ftc.gov so the pattern is on record.
Scam 4: Phishing Links and Fake Payment Pages
The plain “Is this still available?” message is how almost every honest conversation starts, which is exactly why scammers copy it. The trouble comes a few messages later. The “buyer” sends a link to confirm payment, a “shipping label,” or a page that asks you to log in to Facebook so you can get paid. Every one of those links leads to a lookalike page built to steal your password, card number or bank login.
Hijacked accounts make it worse. A message from a friend (“Is this you in this video?”) can come from a scammer who took over their profile. Meta’s new warnings and AI detection help, but they don’t catch everything. If a link asks for a login, a code or a card number, close it and open the real app yourself.
Which Links Should You Never Tap?
| Fake link | What it looks like | What it actually does |
|---|---|---|
| Payment confirmation | A Zelle, PayPal or bank page showing your “deposit” | Captures your bank or app login |
| Shipping label | A courier-style page with a tracking number | Collects your card number or installs malware |
| Facebook “verification” | A copy of the Facebook login screen | Steals your password and takes over your account |
| Policy warning | A message saying your listing or Page will be deleted | Pushes you to an “appeal” form that harvests your details |
- Type the website address yourself instead of tapping a link.
- Check the domain letter by letter. Lookalikes swap one character.
- Turn on two-factor authentication using an authenticator app.
- Never enter a card number to “receive” money. Receiving never needs one.
- Report the profile and the message to Meta before you block.
Scam 5: Fake Listings, Deposits and Non-Delivery
Say you spot a “like-new” laptop in Seattle for $480 when similar ones sell near $800. That’s an illustrative example, but the pattern is real. The photos are lifted from another listing. The seller can’t meet this week, and asks for a $100 deposit so you don’t lose the deal to someone else. Once you pay, the profile vanishes or the account gets deleted.
The FBI separates these into non-delivery (you paid and got nothing) and non-payment (you shipped and never got paid). In 2025 the FBI’s IC3 recorded 56,478 such complaints and about $503 million in reported losses, which works out to roughly $8,900 per complaint on average. The BBB says online purchase scams made up nearly 30% of the 146,000 reports sent to Scam Tracker in 2025.
How Big Can the Loss Get?
| Source | Figure | Period |
|---|---|---|
| FBI IC3, non-payment and non-delivery | 56,478 complaints, about $503.4 million | 2025 |
| FBI IC3, average per complaint (calculated) | About $8,900 | 2025 |
| BBB Scam Tracker, online purchase scams | Nearly 30% of 146,000 reports | 2025 |
| FTC, shopping scams on social media | Most frequently reported social media scam | 2025 |
- Run the photos through a reverse image search such as Google Lens.
- Check how old the profile is and whether it has other listings and friends.
- Ask for a short live video of the item next to a note with today’s date.
- Skip any seller who asks for a deposit before you’ve seen the item.
- Pay on pickup, after inspecting, and not before.
Scam 6: The Pay-First Payment App Trap
Now flip the roles. You’re the buyer, and the seller says “Zelle only” or “send it as Friends and Family on PayPal so I don’t pay fees.” Zelle moves money bank to bank in minutes, and Zelle’s own consumer guidance says that if you authorized a payment, you may not get your money back. Under Regulation E, banks must investigate unauthorized transfers, but a payment you were tricked into sending is usually treated as authorized. Some banks reimburse certain impostor scams. A fake Marketplace seller usually isn’t one of them.
In August 2025, New York Attorney General Letitia James sued Early Warning Services, the company that runs Zelle, saying the network lacked key anti-fraud features. The Consumer Financial Protection Bureau had dropped its own case earlier, and Zelle has called the New York suit a political stunt. Paying through checkout on Facebook is a different story. Meta’s Purchase Protection policy covers eligible purchases up to $2,000 including tax and shipping, with a $10,000 lifetime limit, but local pickups and Messenger transactions don’t qualify.
What Protection Do You Really Have?
| Payment method | If the seller vanishes | Notes |
|---|---|---|
| Cash in person | ❌ No dispute rights | Your protection is inspecting the item first |
| Zelle | ⚠️ Often no refund for payments you authorized | Call your bank right away and ask what it covers |
| Venmo or Cash App | ⚠️ Varies by app and payment type | Read the app’s current policy before paying a stranger |
| PayPal Friends and Family | ❌ Usually no buyer protection | Avoid it with strangers |
| Credit card | ✅ Dispute rights under the Fair Credit Billing Act | Notify the issuer within 60 days of the statement |
| Meta checkout | ✅ Up to $2,000 per eligible purchase | Local pickups and vehicles aren’t covered |
- Refuse “Friends and Family” requests from anyone you haven’t met.
- Use a credit card or checkout for anything shipped.
- Keep payment apps for people you actually know.
- Treat “Zelle only” as a reason to walk away.
Scam 7: Shipping, Fake Tracking and Fee Scams
Shipping scams usually start with a reason the seller can’t meet. He’s deployed, traveling for work, or living two states away in a place like Nashville or Chicago. He’ll ship after you pay. A few days later you get a tracking number that doesn’t work, followed by a message asking for $35 in “insurance” or a “release fee” before the box can move. Real shipping through checkout is one payment, with shipping built in.
Sellers get hit from the other side. A buyer asks you to ship to a cousin’s address, or sends a fake “Marketplace shipping” invoice and pays you through a link. You mail the item, the payment never lands, and the buyer disappears.
How Do You Check Shipping for Real?
| What the scammer says | What is really going on | Your move |
|---|---|---|
| “Pay $35 insurance outside checkout” | Real checkout never adds side fees | Refuse. Pay only inside checkout. |
| “Your tracking number will work tomorrow” | The number is invented | Type it into the carrier’s own site yourself |
| “Send a deposit for shipping” | An advance fee with no item behind it | Walk away |
| “Ship it to my cousin’s address” | Used to move stolen-card or fake-payment goods | Ship only to the address on a verified order |
- Look up every tracking number on the carrier’s official website, never through a link.
- Real tracking normally shows a carrier scan within a day or two, though delays happen.
- Ship only after the money is confirmed in your own account.
- Keep photos of the item, the packing and the receipt.
Scam 8: Car, Truck and Motorcycle Scams
Vehicle scams produce the biggest single losses. BBB spokespeople have described victims who wired or sent app payments and never got the car, with losses ranging from a few hundred to several thousand dollars. A common twist is the fake escrow service: the seller says a third party will hold your money until you approve the car, but the “escrow” site belongs to the scammer. Others ask you to buy prepaid cards “for the escrow.” Wire transfers are especially hard to recover.
Meta’s Purchase Protection excludes vehicles, so there’s no platform safety net here. Title and paperwork rules also vary by state, so check your state’s motor vehicle agency, such as the Texas Department of Motor Vehicles or the California DMV, before you sign or pay anything.
What Should You Check Before Paying for a Vehicle?
| Example vehicle | Example asking price | Illustrative market value | Red flag |
|---|---|---|---|
| 2014 pickup truck, Houston, TX | $6,500 | About $13,000 | Half the usual price |
| 2012 sedan, Charlotte, NC | $2,900 | About $6,000 | Seller “can’t meet, ships by truck” |
| Touring motorcycle, Las Vegas, NV | $5,200 | About $9,500 | Deposit demanded through an app |
These numbers are made-up illustrations of the pattern, not real listings.
- Match the VIN on the car to the title and to a vehicle history report.
- Pull a report through an NMVTIS-approved provider listed at vehiclehistory.gov.
- Inspect and test drive in person, ideally with a mechanic you chose yourself.
- Close the sale at a bank branch so staff can verify the funds.
- As a seller, never sign over the title until the money is confirmed in your account.
- Refuse escrow sites, wire transfers and gift or prepaid cards.
Scam 9: Rental and Housing Scams
The FTC has hard numbers here. Since 2020, people have reported nearly 65,000 rental scams with about $65 million in losses, and the median reported loss was $1,000, according to the FTC’s December 2025 rental scams Data Spotlight. In the 12 months ending June 2025, about half of people who reported a rental scam said it began with a fake ad on Facebook, and another 16% pointed to Craigslist. Adults ages 18 to 29 were three times more likely than other adults to report losing money.
The scammer copies a real listing, swaps in their own contact details and posts it cheaper. Then comes the pressure: pay an application fee, a deposit or the first month’s rent to “hold” the place. Others ask you to screenshot your credit score through a $1 sign-up that quietly starts a paid membership, or to send a Social Security number and driver’s license photo. Young renters hunting sublets in Facebook groups, a common setup in college towns like Tempe, Arizona or Columbus, Ohio, are frequent targets.
What Does a Rental Scam Cost?
| What they ask for | Example amount | Why it is a red flag |
|---|---|---|
| Application fee | $50 to $100 (estimate) | Charged before you’ve seen the unit |
| Security deposit | Around $1,000 (FTC median reported loss) | Real landlords don’t take deposits for unseen homes |
| First month’s rent | $1,200 to $2,500 in cities like Denver or Austin (estimate) | Paid by app or wire to a stranger |
| Credit check “sign-up” | $1 that turns into a recurring fee | Landlords pull credit themselves |
- Search the address. The same home listed for sale or at a different price is a bad sign.
- Compare the rent with nearby listings. A price far below the neighborhood is a warning.
- Don’t share your Social Security number or credit score before agreeing to rent.
- See the property in person, or have someone you trust do it.
- Walk away from any pressure to decide today.
Scam 10: Bait-and-Switch, Counterfeit and Stolen Goods
Sometimes the scam is right in front of you. A “new, sealed” PlayStation turns out to have an open box and a broken disc drive. A $120 pair of “authentic” sneakers is a knockoff. A phone looks perfect until you learn it’s locked to someone else’s account or reported lost. Meta’s own guidance names items that aren’t as described as one of the main forms of marketplace fraud.
This kind of scam depends on rushing you. The meetup is in a dark parking lot, the seller says another buyer is on the way, and you hand over cash before you’ve powered anything on. A slow, calm test beats nearly every trick on this list.
What Should You Test Before You Pay?
| Item | What to test before paying | Time needed (estimate) |
|---|---|---|
| iPhone or Android phone | Power on, check Activation Lock or account removal, compare serial or IMEI with the box | 5 to 10 minutes |
| Laptop | Boot it, check battery health, ports and screen | 10 minutes |
| Game console | Run a game or disc, test controllers and ports | 10 minutes |
| Designer sneakers or bags | Compare stitching, tags and box details against official photos | 5 minutes |
| Furniture | Look for stains, bed bugs, wobble and odor | 5 minutes |
- Meet where there’s light and cameras, and test the item on the spot.
- Bring a friend if the item costs more than a few hundred dollars.
- Ask for the original receipt or box on anything marketed as new.
- Be ready to walk away if the seller won’t let you test it.
What Do These Scams Cost, and What Does Protection Cost?
The headline numbers are big, but they come from different agencies that count different things. The FTC tallies consumer fraud reports. The FBI tallies internet crime complaints. The BBB tallies what people submit to Scam Tracker. None of them captures every victim, so read these as floors, not ceilings (figures as of October 2026).
| Source | Number | What it measures |
|---|---|---|
| FTC, all consumer fraud, 2025 | $15.9 billion from 3 million reports | Reported fraud losses of every type |
| FTC, social media contact, 2025 | $2.1 billion | Losses where the scam started on social media |
| FTC, Facebook alone, 2025 | About $794 million | More than text and email scams combined |
| FBI IC3, all internet crime, 2025 | About $20.9 billion from 1,008,597 complaints | Every type of reported cybercrime |
| FBI IC3, non-payment and non-delivery, 2025 | About $503.4 million from 56,478 complaints | The buy-and-sell scams in this guide |
| FTC, rental scams since 2020 | About $65 million, median loss $1,000 | Fake rental listings, mostly on Facebook |
Protection itself is cheap. Reporting a scam is free, reverse image searches are free and bank alerts are free. What can cost money is a vehicle history report, an authenticator or password manager upgrade, or a credit card with an annual fee. Here’s a quick view of what you might pay.
| Protection | Typical cost | Free or paid? |
|---|---|---|
| Reverse image search (Google Lens) | $0 | Free |
| Bank and card alerts | $0 | Free |
| Authenticator app for two-factor login | $0 | Free |
| Vehicle history report | A few dollars to about $40 (estimate) | Paid |
| Credit card with dispute rights | $0 on many cards, higher on premium cards | Free to paid |
US Rules That Decide Whether You Get Your Money Back
Your odds of a refund depend less on how smart the scammer was and more on how you paid. Federal rules and agencies draw the lines, and some details change from state to state, so confirm anything big on the official site or with a qualified professional. This is general information, not legal advice.
| Rule or agency | What it covers | What it means on Marketplace |
|---|---|---|
| Regulation E (CFPB) | Unauthorized electronic transfers from bank accounts | A payment you were tricked into sending is often treated as authorized, so refunds aren’t guaranteed |
| Fair Credit Billing Act (enforced by the FTC) | Billing errors on credit cards, including goods never delivered | Dispute in writing within 60 days of the statement date. It doesn’t cover debit cards. |
| Meta Purchase Protection (platform policy, not a law) | Eligible checkout purchases up to $2,000, $10,000 lifetime | No cover for local pickups, Messenger deals or vehicles |
| FTC and ReportFraud.ftc.gov | Collects fraud reports and shares them with law enforcement | Report even small losses so patterns show up |
| FBI Internet Crime Complaint Center (IC3) | Internet crime including non-payment and non-delivery | Report larger losses and wire transfers here |
| State attorneys general | State consumer protection laws and lawsuits | New York’s Zelle suit is one example. Check your state office for local help. |
| State motor vehicle agencies (for example Texas DMV, California DMV) | Titles, registration and bills of sale | Vehicle paperwork rules differ by state |
Scam Comparison at a Glance
Use this table to see which scams hit hardest and fastest. Dollar ranges are estimates built from the sourced figures above and typical listing prices, not guarantees.
| Rank | Scam | Who it targets | Typical money at risk (estimate) | How fast you lose it |
|---|---|---|---|---|
| 1 | Fake listings and deposits | Buyers | $100 to $1,500, with an IC3 average near $8,900 | Minutes after you pay |
| 2 | Pay-first payment app trap | Buyers | $200 to $2,000 | Instantly |
| 3 | Fake payment notices | Sellers | The item, often $150 to $1,500 | When you hand over the item |
| 4 | Overpayment and fake checks | Sellers | $200 to $1,000 | Days to weeks |
| 5 | Car and vehicle scams | Buyers and sellers | $2,000 to $15,000+ | At payment or title transfer |
| 6 | Rental scams | Renters | About $1,000 median (FTC) | At the “hold” payment |
| 7 | Shipping and fee scams | Buyers and sellers | $30 to $500 | After the first extra fee |
| 8 | Phishing links | Both | Account takeover, bank access | At the click |
| 9 | Google Voice code | Sellers | No direct loss, but identity risk | The moment you read the code |
| 10 | Bait-and-switch and counterfeit | Buyers | $50 to $1,200 | At the meetup |
Safe Meetups: Where to Trade in Columbus, Atlanta, Austin and Beyond
Scams aren’t the only risk. Meeting a stranger with a phone, a bike or a stack of cash brings its own danger. Meta advises meeting in a public, well-lit place and not changing the agreed location at the last minute. Many US police departments go a step further and mark off parking spaces for online trades.
Columbus, Ohio is a clear example. The city’s official safe exchange zone page lists five monitored Internet Purchase Exchange Zones at police sub-stations, each covered by a city-owned video camera. Atlanta police have said monitored safe exchange zones are located at every police precinct. In the Austin area, the Cedar Park and Round Rock police departments both offer camera-monitored exchange spots, and a local TV report counted eight departments there with similar zones.
| City | What exists | Tip |
|---|---|---|
| Columbus, OH | Five monitored zones at police sub-stations | Stand near the posted sign so the camera covers you |
| Atlanta, GA | Safe exchange zones at police precincts | Confirm the precinct and hours with APD first |
| Austin area, TX | Cedar Park and Round Rock police exchange spots | Use the spots near the station entrance |
| Tampa, FL | Hillsborough County Sheriff’s Office designated Safe Exchange Zones | Call to confirm current locations |
| Phoenix, AZ, Denver, CO and others | Many departments offer similar spots | Search “[your city] police safe exchange zone” |
- Meet in daylight whenever you can.
- Tell someone where you’re going and who you’re meeting.
- Bring a friend for anything worth several hundred dollars.
- Keep the item and your phone in sight, and count cash before you hand over goods.
- If the seller changes the location at the last minute, cancel.
Where to Report a Scam in the USA
Report quickly and report to more than one place. Each agency uses reports for something different, and your bank can only help if you reach it fast. Save screenshots, usernames, payment receipts and the listing link before you report, because scammers delete accounts.
| Where | Best for | How it works | Free? |
|---|---|---|---|
| Facebook or Meta (in-app report) | Removing the listing or profile | Open the listing or profile, choose Report, then Scam | ✅ Free |
| FTC at ReportFraud.ftc.gov | Every type of scam | Online form, and your report goes into the Consumer Sentinel database | ✅ Free |
| FBI IC3 at ic3.gov | Non-payment, non-delivery and larger losses | Online complaint form for internet crime | ✅ Free |
| Your bank or card issuer | Trying to stop or reverse a payment | Call the number on your card right away | ✅ Free |
| BBB Scam Tracker | Warning other buyers and sellers | Submit a report at BBB.org/ScamTracker | ✅ Free |
| Local police | Robbery, threats and in-person crime | File a report, which also helps with bank paperwork | ✅ Free |
| State attorney general | Consumer complaints, for example in Texas or Florida | Online complaint form on the state site | ✅ Free |
| CFPB complaint | A bank that mishandled your dispute | Online complaint at consumerfinance.gov | ✅ Free |
How to Protect Yourself: Step by Step
- Check the profile first. Look at account age, friends, past listings and ratings before you reply.
- Keep the chat in Messenger. Moving to text or email removes evidence and invites links and codes.
- Price-check the item. A listing far below market on eBay or Google Shopping needs a hard look.
- Pick a protected way to pay. Use cash in person, Meta checkout or a credit card.
- Confirm money in your own app. Never trust a screenshot, email or link.
- Meet somewhere safe. A police exchange zone or a busy, well-lit place beats a driveway.
- Save evidence and report fast. Call your bank first, then report to Meta, the FTC and, where it fits, the FBI.
Real Stories: Buyers and Sellers Across the USA
These are made-up examples based on common patterns. They are not real people or real results.
Story 1: Maria, 34 — Nurse, Phoenix, Arizona
Maria listed a stroller for $280. A buyer offered a $480 check and asked her to send back $200 for “a courier.” She deposited it, saw the funds appear, and almost sent the money. Then she remembered a warning about checks that look good but aren’t. She waited, and about a week later her bank reversed the deposit. Because she hadn’t sent anything, she lost nothing but time.
Story 2: Derek, 27 — Warehouse worker, Columbus, Ohio
Derek found a gaming PC for $1,150, nearly $400 below similar listings. The seller wanted Zelle and refused to meet. Derek paid, and the profile disappeared within the hour. His bank said he had authorized the payment, and he spent two weeks filing reports with the FTC and a CFPB complaint. He never recovered the money. Now he buys only at Columbus police exchange zones, with cash, after testing the item.
Story 3: Tasha, 41 — Teacher, Atlanta, Georgia
Tasha saw a two-bedroom rental in Atlanta listed at $1,350 a month, well under nearby rents. The “landlord” was out of town and asked for a $1,000 deposit to hold it, plus a screenshot of her credit score. She searched the address, found it listed for sale elsewhere, and stopped. She reported the listing to Meta and the FTC and kept her deposit.
Story 4: Jake, 52 — Contractor, Tampa, Florida
Jake found a pickup truck for $14,500 in Tampa when similar trucks ran near $22,000. The seller pushed an “escrow service” and said another buyer was waiting. Jake insisted on seeing the truck and closing at his bank. The seller stopped replying. Jake lost an afternoon of messaging and no money.
Red Flags and Mistakes to Avoid
- A price that’s too good. If a $900 phone costs $350, someone is hiding something.
- Pressure to move fast. “Another buyer is waiting” is a way to stop you from thinking.
- Requests for codes. No real buyer or seller needs your verification code.
- Off-platform payment demands. Zelle only, gift cards, wire transfers and crypto are all warnings.
- Refusing to meet or video chat. A real seller can show the item.
- Brand-new accounts. Empty profiles with stolen photos appear constantly.
- Clicking “confirm payment” links. Check the payment in your own app.
- Skipping the test. Handing over cash before powering the item on is the classic bait-and-switch mistake.
- Waiting to report. Every day you wait lowers the chance anyone can stop the money.
Free and Paid Tools That Help
| Tool | What it does | Free or paid? | Why you need it |
|---|---|---|---|
| Google Lens or reverse image search | Shows whether a photo appears elsewhere | Free | Catches stolen listing photos |
| Your bank’s app and alerts | Shows real deposits and flags unusual activity | Free | The only true proof a payment arrived |
| Authenticator app | Adds two-factor login to Facebook and email | Free | Blocks account takeovers |
| Password manager | Creates and stores unique passwords | Free tiers exist, paid plans about $2 to $5 a month (estimate) | Limits damage if one account leaks |
| Vehicle history report (NMVTIS-approved providers) | Shows title, damage and odometer records | Paid, a few dollars to about $40 (estimate) | Confirms a car is what the seller says |
| Apple coverage check or carrier IMEI check | Checks a phone’s status and warranty | Free | Spots locked or reported phones |
| BBB Scam Tracker search | Lets you look up reported scam tactics | Free | Shows what’s trending in your area |
| Credit card with dispute rights | Lets you challenge undelivered goods | $0 annual fee on many cards | Strongest recourse for card purchases |
✅ Quick Reference Checklist — Your Action Plan
| ☐ | Action step | Priority | When to do it |
|---|---|---|---|
| ☐ | Never share a verification code with a buyer or seller | 🔴 Critical | Always |
| ☐ | Confirm payment inside your own app before handing over anything | 🔴 Critical | Before every handoff |
| ☐ | Refuse checks and payments above the asking price | 🔴 Critical | When selling |
| ☐ | Use cash, credit card or Meta checkout, not “Zelle only” | 🔴 Critical | Before paying |
| ☐ | Meet at a police exchange zone or busy public spot | 🟠 High | Before every meetup |
| ☐ | Test the item before paying | 🟠 High | At the meetup |
| ☐ | Reverse-search listing photos | 🟠 High | Before replying |
| ☐ | Run a vehicle history report on any car | 🟠 High | Before wiring or paying |
| ☐ | Turn on two-factor authentication | 🟡 Medium | This week |
| ☐ | Save ReportFraud.ftc.gov and your bank’s fraud number | 🟡 Medium | Today |
Frequently Asked Questions (FAQ)
1. What are the most common Facebook Marketplace scams in the USA right now?
The most common are fake payment notices, overpayment checks, Google Voice code requests, phishing links, fake listings with deposits, payment app traps, shipping fee tricks, car scams, rental scams and bait-and-switch deals. Sellers mostly face fake payments and fake checks, while buyers mostly face fake listings and deposit demands. The FTC says shopping scams were the most reported kind of social media scam in 2025. The FBI also logged 56,478 non-payment and non-delivery complaints that year. If a deal pushes you toward an unusual payment method or a rushed timeline, treat that as your warning. Each scam above comes with a safer alternative.
2. Is Facebook Marketplace safe to use in the US?
It can be reasonably safe if you treat every stranger as unverified. Millions of Americans trade furniture, bikes and electronics without trouble. But the numbers show real risk. The FTC says Facebook led every social platform in reported scam losses in 2025, and BBB data puts online purchase scams near 30% of Scam Tracker reports. Safety comes down to payment method, meetup location and how well you spot pressure. Cash in a monitored spot, or a credit card, gives you the best footing. Skip anything that drags you into links, codes or strange payment apps.
3. Will Meta refund me if I get scammed on Marketplace?
Only for eligible purchases paid through checkout on Facebook. Meta’s policy covers a purchase price up to $2,000 including tax and shipping, with a $10,000 lifetime coverage limit, and approved claims are generally refunded the item price and shipping. Local pickups, Messenger transactions and third-party sites don’t qualify, and vehicles and rentals are excluded. So a $450 couch you pay for in cash isn’t covered. Read the current policy on Meta’s help center before relying on it.
4. Can I get my money back from Zelle if a Marketplace seller scammed me?
Possibly not, because banks often treat a payment you sent yourself as authorized. Zelle’s own guidance says you may not be able to recover money you authorized. Call your bank immediately, using the number on your card, and ask whether your case qualifies under its policy. Then report to the FTC and the FBI’s IC3, and file a CFPB complaint if the bank brushes you off. New York’s attorney general sued Zelle’s operator in August 2025, but that case doesn’t promise you a refund. Policies differ by bank, so ask for the decision in writing.
5. Where do I report a Marketplace scam in the USA?
Start with your bank, then Meta, the FTC at ReportFraud.ftc.gov and the FBI’s IC3. You can add BBB Scam Tracker to warn others and your state attorney general for local help. Report to local police if there was a threat, robbery or in-person crime. Gather screenshots, receipts, usernames and the listing link first. Speed matters most with banks, because payments get harder to recall each day. Filing in several places also helps agencies spot patterns across states like Texas, Florida and Arizona.
6. Is it safe to give a buyer my phone number or a verification code?
Never share a verification code, and be careful with your number. The FTC warns that a Google Voice code lets a scammer create a number linked to yours. A real buyer can message you through Messenger and doesn’t need your phone. If you already sent a code, follow Google’s steps to reclaim your number and watch for odd calls or texts. Change passwords on accounts that use that number. Report the buyer’s profile so Meta can act on it.
7. Does my city have a police safe exchange zone?
Many do. Columbus, Ohio lists five monitored zones at police sub-stations, and Atlanta police have said every precinct has one. The Austin area has spots at Cedar Park and Round Rock, and Hillsborough County in Florida has designated zones around Tampa. Other cities and counties run similar programs, so search for your city plus “police safe exchange zone.” Call the non-emergency number to confirm hours and locations before you go. If your area has none, a busy, well-lit public spot is your next best choice.
8. Can I dispute a Marketplace payment on my credit card?
Often yes, if you paid by credit card. The Fair Credit Billing Act lets you dispute billing errors, including goods never delivered, within 60 days of the statement that shows the charge. Send the dispute in writing to the billing-inquiries address on your statement. The issuer must acknowledge it within 30 days and resolve it within two billing cycles, no longer than 90 days. The law doesn’t cover debit cards, so cards and debit differ a lot here. Most private Marketplace sellers can’t take cards, so this mainly helps with checkout and PayPal-funded purchases.
Final Thought
Most scams on this list die the moment someone slows down. A seller in Phoenix who checks her own bank app before handing over the couch is safe. So is a renter in Houston who refuses to wire a deposit for a home he hasn’t seen.
None of this means you should quit Marketplace. A Denver family can still find a $200 bike for their kid, and a Charlotte seller can still clear out the garage. The platform is useful. It just comes with no guarantees.
What changes your odds is a short set of habits. Verify money in your own app, keep the chat in Messenger, meet in public and never read out a code. Those habits cost nothing and work in every state.
And if something does go wrong, speed is your friend. Call your bank first, then file your reports. The sooner you act, the better the chance someone can help.
Start today: open your listings and messages, delete any chat that asked for a code or a link, and bookmark ReportFraud.ftc.gov on your phone. Then pick one safe exchange spot near you and use it for your next sale.
Know someone who buys or sells on Marketplace? Send them this guide before their next deal.
Disclaimer: This guide is for general education, not legal, financial or tax advice. Figures come from the sources named and from estimates labeled as such, and they change over time. Results and refunds are not guaranteed. Rules and protections vary by state, bank and payment provider, so confirm details with official sources or a qualified professional.